
Our Method
The 5 Points of Compliance
Our 5 Points of Compliance Method examines the entire credit reporting and challenge process—not simply whether an account is accurate.
Metro 2 Compliance
Metro 2 is the standardized reporting format used by furnishers to report consumer credit information to the major credit reporting agencies. We review whether information is being reported consistently with applicable Metro 2 standards and credit reporting requirements.
Metro 2 is the industry-standard format that banks, lenders, collection agencies, and other data furnishers use to transmit consumer account information to Equifax, Experian, and TransUnion. It governs how account status, payment history, balances, dates, and consumer identifiers are coded and transmitted. When a furnisher reports data that does not conform to Metro 2 standards, the information on the consumer’s credit file may be incomplete, inconsistent, or misleading. We review reported accounts for these formatting and reporting-standard issues and, where appropriate, challenge the furnisher to substantiate that it has complied with the applicable reporting requirements.
Credit Reporting Agency Status
We examine whether the organization involved meets the applicable definition of a Consumer Reporting Agency (CRA) and whether it is operating in accordance with the requirements that apply to that role.
Under the Fair Credit Reporting Act, a Consumer Reporting Agency assembles and evaluates consumer credit information for purposes such as credit, insurance, or employment. CRAs are subject to specific obligations regarding accuracy, dispute handling, reinvestigation, and consumer access. We examine whether the entities reporting and maintaining the information meet the applicable definition of a CRA and whether they are fulfilling the responsibilities that role requires, including the duty to provide accurate information and to conduct reasonable reinvestigations when a consumer disputes an item.
Notice to the Data Furnisher
When a consumer challenges information through a credit bureau, the bureau must notify the data furnisher that reported the information and provide the relevant information necessary for the furnisher to investigate.
When a consumer files a dispute with a credit bureau, the FCRA requires the bureau to notify the furnisher that originally reported the information within five business days. The bureau must also provide the furnisher with all relevant information the consumer submitted about the dispute. This notice triggers the furnisher’s legal obligation to investigate. We review whether the bureau properly notified the furnisher and whether it transmitted the information necessary for a meaningful investigation, because failures in this step can affect the validity of the reported information.
Furnisher Investigation and Response
After receiving the challenge, the data furnisher must investigate the challenged information, review the relevant information provided, and report the results back to the credit reporting agency that initiated the process.
Once a furnisher receives a dispute notice, the FCRA requires it to conduct a reasonable investigation, review and consider all information the consumer provided, report its findings back to the credit bureau, and correct or delete any information it cannot verify. The investigation must be completed generally within 30 days. We examine whether the furnisher actually conducted a substantive investigation, whether it reviewed the relevant documentation, and whether it can demonstrate that it verified the information rather than simply restating what it already had on file.
Action Across Relevant CRAs and Data Furnishers
Any required action resulting from the investigation must also be communicated to the relevant credit reporting agencies and data furnishers involved, where required, even if the consumer did not directly contact each of them.
When a furnisher determines that information is inaccurate or cannot be verified, it must not only correct it with the bureau that sent the dispute, but also notify all other credit reporting agencies to which it furnished the same information. This ensures that corrections are reflected across the consumer’s entire credit profile, not just at one bureau. We monitor whether furnishers and bureaus properly propagate corrections and deletions across all relevant agencies, so that a resolution achieved through one channel is reflected throughout the consumer’s credit file.
A Different Approach to Credit Repair
Most traditional credit repair focuses on one question:
Is the information on your credit report inaccurate?
That can be appropriate when something is genuinely wrong. But correcting one inaccurate detail does not necessarily remove the underlying negative account.
At Tony's Credit Repair, our primary programs use what we call the 5 Points of Compliance Method. Instead of focusing only on whether an account is yours or whether a specific detail is accurate, we also examine how negative information is being:
The goal is to identify potential reporting or compliance issues and challenge negative information based on the standards and requirements that may apply.
Why We Don’t Rely Solely on Traditional Disputes
A traditional dispute usually tells the credit bureau exactly what the consumer believes is wrong. For example:
- A late payment is incorrect
- A balance is wrong
- An account does not belong to the consumer
- An account status is being reported incorrectly
The bureau and data furnisher then investigate that specific issue. But if the item is verified, repeating the same dispute may not get you very far.
A Real TransUnion Example
In an actual TransUnion response, the bureau stated that it had already investigated the items and that the data furnishers had verified the information.
TransUnion then explained that unless the consumer provided additional relevant information supporting the requested change, it was not required to reinvestigate the same items again at that time. Examples TransUnion provided included:
- A letter from the creditor or courthouse
- A billing statement
- A letter from the IRS
- A canceled check
- A money order showing payment
- Other relevant supporting information
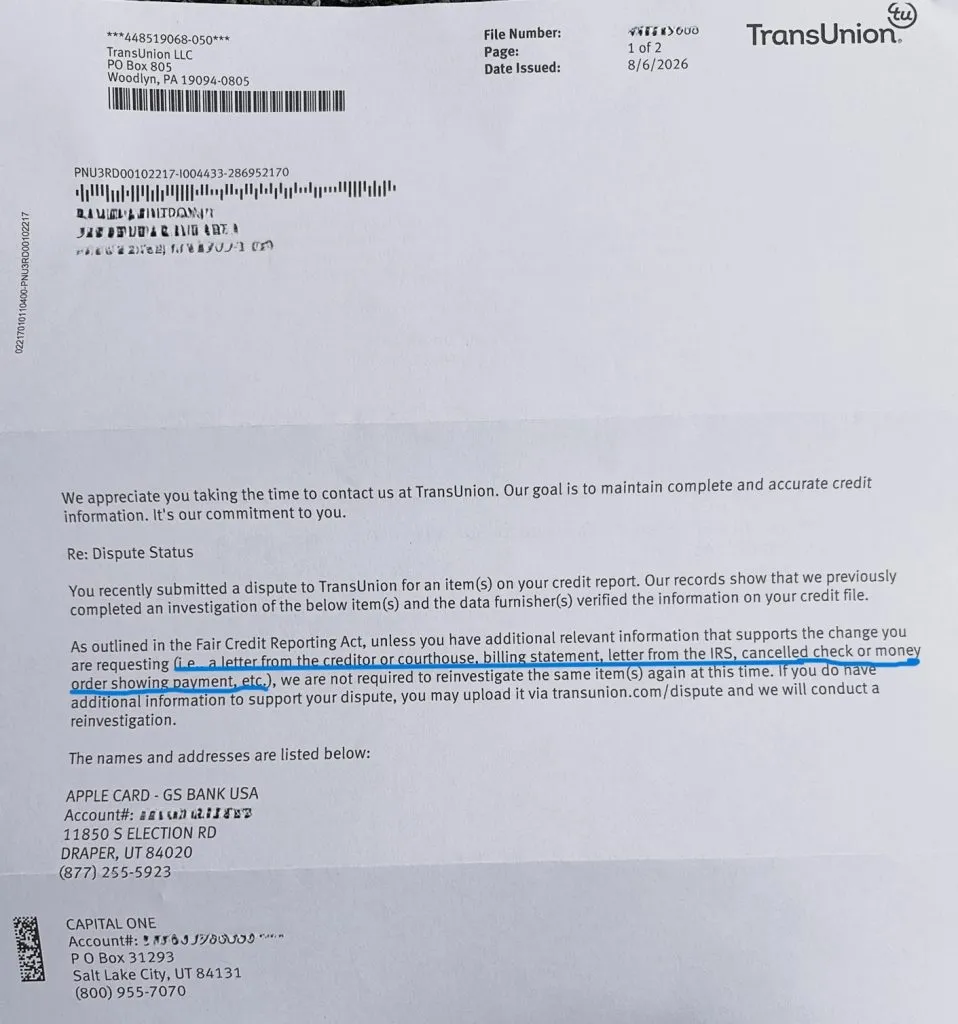
Actual TransUnion correspondence showing additional relevant information may be needed before the negative items are reinvestigated.
Why That Matters
If you are saying something is inaccurate, the question becomes:
What new evidence do you have showing that it is inaccurate?
If the account actually belongs to you, the late payment really happened, or the collection is legitimate, you may not have new documentation proving otherwise.
That is why our primary programs go beyond simply sending disputes and instead focus on a broader compliance-based review.
Traditional Dispute vs. Compliance-Based Challenge
Traditional dispute
“This information is inaccurate. Please investigate and correct it.”
Compliance-based challenge
“Is this information being reported, processed, investigated, and maintained in accordance with the standards and requirements that apply to it?”
That is the key difference.
A negative account can be legitimate and still warrant review of how it is currently being reported and handled.
What Does This Mean for You?
You do not need to become an expert in Metro 2 or credit reporting procedures.
That is the work we handle.
We review your credit profile, identify the negative accounts affecting your report, prepare the appropriate challenges, review the responses, and determine the next step based on what happens.
The process is individualized to the consumer and the reporting involved.
A More Formal Approach Without Attorney-Level Costs
Think of the difference this way:
A basic dispute is often a request to correct a specific fact.
Our compliance-based approach is more structured.
We prepare detailed correspondence focused on the reporting process, applicable standards, the parties involved, and the responses that follow.
It is somewhat similar to why a formal letter prepared by an attorney may receive more attention than a casual complaint.
Not because we are attorneys or because our correspondence has the legal authority of a subpoena or court order.
It does not.
The comparison is in the structure, documentation, preparation, and follow-up.
Hiring an attorney to individually review credit-reporting issues, prepare correspondence, analyze responses, and continue following up can become expensive very quickly.
Our service provides consumers with a structured, compliance-focused process at a fraction of what individualized legal representation could cost.
Tony's Credit Repair is not a law firm and does not provide legal advice or legal representation.
Every credit file is different. We do not promise specific deletions, score increases, or exact timelines. Our goal is to identify legitimate reporting and compliance issues and pursue the strongest available strategy for each client.
Ready to See What May Be Holding Back Your Credit?
We’ll review your situation, discuss your goals, and explain which approach may make the most sense for you. Start with a Free Credit Health Check.
Schedule a Free Consultation